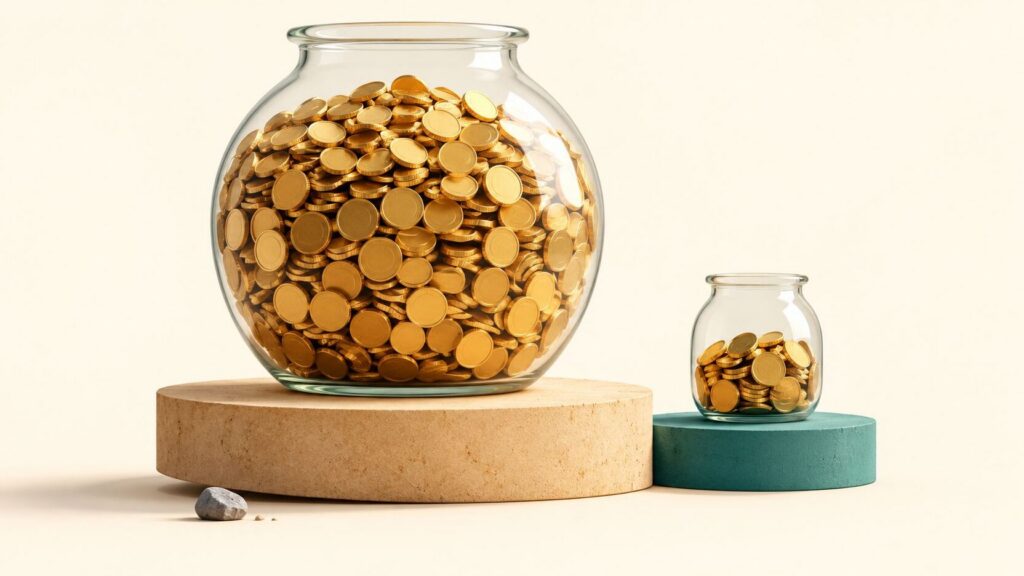
Illustrative AI image; it does not depict the size or performance of an actual fund.
A fund with many thousands of crores in AUM can feel reassuring. Surely that much money means less risk? Size is useful information, but it does not stop share prices falling, prevent a bond issuer from encountering difficulty or remove an investor’s need to sell at an inconvenient time. Understand the measure before treating it as a safety certificate.
Three points to remember
- AUM describes the scale of assets managed, not a guarantee of your capital.
- AUM growth can reflect new inflows rather than better investment returns.
- Interpret size alongside strategy, underlying assets, liquidity and concentration.
Whose money does AUM represent?
AUM stands for Assets Under Management. SEBI’s investor material explains it in terms of managed assets. A scheme’s AUM, the total AUM across an AMC and the AMC’s own net worth are distinct measures. Different schemes from one large fund house can have very different portfolios and risks. Source: SEBI Investor, mutual-fund concepts.
A scheme AUM of ₹20,000 crore does not mean the AMC has set aside that much of its own money to compensate your losses. It describes the scale of pooled investments. Nor is high AUM a form of bank-deposit insurance. AMFI’s risk information states that mutual funds are not guaranteed or assured-return products and identifies risks including possible loss of principal. Source: AMFI risk factors.
Can AUM grow while the investor earns nothing?
Take a simplified hypothetical fund with opening AUM of ₹1,000 crore. Assume no market-value movement, expenses or other adjustments. Investors add a net ₹200 crore. Closing AUM is ₹1,200 crore, a 20% increase. Yet the existing investor’s investment return in this model is zero.
Reverse the situation: market movement takes ₹1,000 crore to ₹1,100 crore, followed by net redemptions of ₹150 crore. Closing AUM becomes ₹950 crore. The fund is smaller despite a simplified investment gain of 10% before those redemptions. Real reconciliation also needs flow timing, valuations and other adjustments. Opening and closing AUM alone cannot establish performance.
The same percentage loss still matters
Fund A manages ₹10,000 crore and Fund B ₹1,000 crore. Suppose both portfolios fall 20% over a hypothetical period and you hold ₹1 lakh in each. Both holdings become ₹80,000. A larger fund does not reduce the percentage represented by your ₹20,000 loss. The illustration isolates size from percentages; it does not assert that any two actual funds have identical risks.
NAV movements affect the value of your units. A large fund-level rupee loss can sound alarming while a large AUM can sound comforting, but neither headline replaces your own percentage exposure, horizon and ability to absorb losses.
When does size become a useful question?
Scale may help spread some operating costs, but check actual charged expenses before assuming a benefit. A longer record and established processes can be useful, yet AUM alone does not measure their quality. Conversely, deploying or selling large sums in less-liquid securities can create execution challenges. That is strategy-specific, not proof that every large fund is bad or every small fund easy to manage.
In a numerical illustration, a 1% position in a ₹10,000 crore fund is ₹100 crore; the same weight in a ₹1,000 crore fund is ₹10 crore. Orders in the same security would have different sizes. Without trading-volume and market-depth information, neither amount establishes how many days liquidation would take. Both “large means liquid” and “large means trapped” are incomplete claims.
For available small-cap and mid-cap liquidity disclosures, see AMFI’s official stress-test disclosure page. These disclosures do not guarantee the outcome of every future redemption.
Read this dashboard alongside AUM
- Scheme-level AUM and its date, without confusing it with the AMC total.
- Underlying asset class, concentration and, for debt, issuer and credit exposure.
- Current risk disclosures in relation to your own horizon.
- Available information about liquidity management, cash and redemption patterns.
- Mandate, costs and performance compared within an appropriate category.
- Overlap with your other investments and overall portfolio risk.
A universal “ideal AUM range” is not useful across all categories. A broad liquid-market strategy, a concentrated smaller-company strategy and a debt strategy can have different capacity constraints. Identify the fund’s role before asking which aspects of size matter.
Separate a documented observation from a story. “AUM rose this quarter” is an observation. “Investors now consider it safe” is an interpretation requiring additional evidence. A disciplined comparison avoids turning a large number into an unsupported explanation.
Three common questions
Does high AUM demonstrate popularity?
It shows total managed value. Investor count, retail popularity and current inflows are separate data points that need evidence.
Does falling AUM mean a fund became poor?
No. Separate market movements from investor flows before interpreting the change.
Is a small fund always riskier?
No. Holdings, strategy and operations matter. Size is one input rather than a complete decision.
The takeaway
Read AUM as portfolio scale, not capital protection. Understanding the goal, underlying risk and liquidity is more useful than being impressed by the number of crores.
Risk and disclosure: This article is for financial education, not personalised investment advice or a recommendation to buy a fund. Historical NAV-based results do not guarantee future returns. Mutual fund investments are subject to market risks. I am an AMFI-registered Mutual Fund Distributor and may receive commission when you invest in Regular Plans through my distributor link. Read the scheme documents and consult a SEBI-registered investment adviser when you need personalised advice.
सभी टिप्पणियाँ / All Comments
No published comments yet.
Related reading
Some linked articles are in Hindi.
 IDCW मिला: क्या ये पूरा मुनाफा है? →
 Gold Has Fallen: Check This Before You Buy →
 Smallcap गिरे तो SIP रोकें या जारी रखें? →
 Small-Cap ETF vs Active Fund: Is Cheaper Really Better? →
 SIP का असली रिटर्न कितना? XIRR और Absolute Return समझें →
चर्चा / Comments