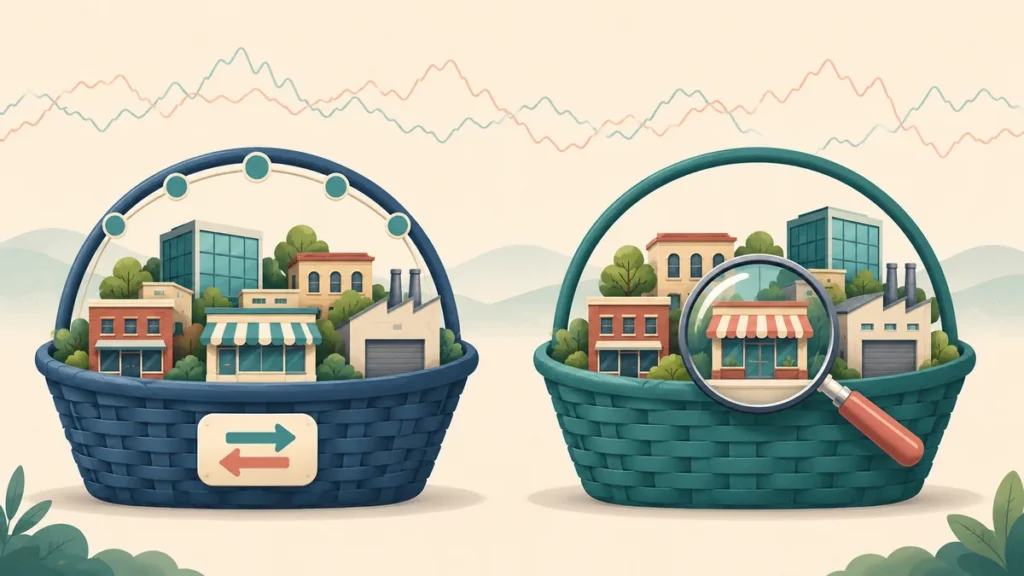
AI द्वारा बनाया गया चित्र
A small-cap ETF’s low fee can look attractive. An active small-cap fund offers a manager’s judgement. Choosing between them requires more than comparing expense ratios: match the exposure, then examine execution costs, tracking and risk. A small-cap index mutual fund is a third option for a simple SIP.
My older ETF video raises a useful question: is buying an ETF better, or should an investor choose a small-cap mutual fund? No single label answers that. Start with the companies you will own and how those companies are selected.
Understand the three choices first
- Small-cap ETF: this article discusses passive ETFs tracking a small-cap index. Ordinary retail purchases and sales take place on an exchange through demat and trading accounts.
- Active small-cap mutual fund: a manager selects companies and portfolio weights within the scheme’s mandate. The manager may aim to beat the index, but success is not assured.
- Small-cap index mutual fund: this is also passive, with ordinary mutual-fund investing and amount-based SIP facilities. You do not have to choose an exchange execution price for each purchase.
ETF describes a trading structure; active and passive describe how a portfolio is managed. “ETF versus mutual fund” is therefore incomplete: an ETF can itself be a mutual-fund scheme. Tata Mutual Fund’s ETF guide explains these distinctions.
Why a Nifty 50 ETF is not a fair small-cap comparison
If one portfolio owns large companies and the other small companies, the return gap cannot be attributed only to the ETF structure or the fund manager. Match small-cap exposure and the benchmark first. Nifty Smallcap 250 represents companies ranked 251–500 by market capitalisation within Nifty 500. It is not a list of every Indian small-cap company.
A real structural example is the Motilal Oswal Nifty Smallcap 250 ETF alongside the AMC’s Nifty Smallcap 250 Index Fund. Both seek to track Nifty Smallcap 250 TRI. Comparing these helps isolate the ETF-versus-ordinary-index-fund structure. These names are examples, not purchase recommendations.
An active small-cap fund will hold a different portfolio. SEBI’s categorisation circular dated 26 February 2026, page 3, requires the small-cap category to invest at least 65% of total assets in small-cap equity and equity-related instruments. This does not require an active fund to hold the index’s exact stocks or weights.
Can a low-fee ETF still cost more?
Sometimes execution costs reduce the benefit of a lower annual fee. Alongside TER, examine brokerage, applicable exchange and statutory charges, demat charges and the bid–ask spread. The spread is the gap between buyers’ bids and sellers’ asking prices. The last traded price on screen does not guarantee that your whole order will trade at that price.
An ETF’s market price can be above or below NAV or indicative NAV. Check available quantity, spread and premium or discount before placing an order. A limit order controls the price you are willing to accept; it does not guarantee execution. SEBI’s ETF introduction explains exchange trading and additional costs.
A hypothetical cost illustration: on a constant average holding of ₹1 lakh, an annual expense of 0.30% is approximately ₹300, while 0.90% is approximately ₹900. The difference is ₹600 a year. These are invented rates, not the current fees of any named scheme. ETF transaction costs can be additional, and the portfolios may earn different returns. The ₹600 is not a guaranteed net benefit.
For a DIY comparison, examine the active fund’s Direct Growth option too. Comparing an ETF only with a Regular plan’s expenses can distort the conclusion. AMFI explains that Direct plans cost less than the same scheme’s Regular plans because distribution commission is absent. If choosing a Regular plan with assistance, understand both the cost and the service received.
Match these five things when comparing returns
- The same periods and dates: do not compare a three-year return with a ten-year return. For SIPs, match cash-flow dates and amounts too.
- The right benchmark: use a TRI that includes dividends. Different small-cap indices may use different selection and weighting rules.
- The plan and option: specify Growth, Direct or Regular and the applicable costs. Published NAV returns already reflect TER; do not subtract it again.
- The ETF investor’s experience: NAV performance can differ from returns based on your exchange purchase and sale prices.
- Losses as well as gains: examine different market cycles, rolling periods, drawdowns and recovery. Picking only the best past year is insufficient.
For passive products, tracking difference is the fund-versus-benchmark return gap over a period. Tracking error measures the variability of return deviations. Low tracking error does not mean low market risk. SEBI’s tracking-error explainer provides the statistical definition.
Small-cap risk remains in both
A low ETF fee does not protect against sharp falls. An active manager can avoid some companies or change allocations, but that does not guarantee smaller losses or better returns than the index. Difficult liquidity in underlying small-cap shares can affect either approach. ETFs also involve exchange execution.
Before allocating money needed for essential spending in the next few years, an emergency fund, or money whose large decline you cannot tolerate, consider whether small-cap exposure is appropriate at all. SIP discipline can help behaviour; it does not eliminate losses. Frequent trading in response to daily prices can produce a poor experience even in a cheap product.
Which route may fit which investor?
- Consider a small-cap ETF: you want a chosen index, use demat, understand spreads and execution, and find competitive all-in costs and tracking.
- Consider an active small-cap fund: you have a clear reason to trust its selection process and can accept its fees, manager risk and possible prolonged underperformance.
- Consider a small-cap index fund: you want passive exposure, but fixed-rupee SIP convenience and avoiding exchange orders matter more. Its TER, tracking and scheme terms still need scrutiny.
My view: “the ETF is cheaper” or “the small-cap fund performed better before” is not enough. Choose the appropriate exposure first, then passive or active management, and finally weigh total costs and convenience. No route is right for everyone.
The related older video
Watch my ETF and SIP video published on 6 August 2025 → It discusses daily-price chasing and regular-investing discipline. This article extends that discussion to small-cap exposure, passive and active strategies, and the cost of buying.
Sources checked: 10 November 2026. This article does not claim current scheme TERs, live spreads or a verified historical-return ranking. Named products illustrate structure only. This is financial education, not personal investment advice. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Capital losses are possible; past performance does not guarantee future returns.
All Comments
No published comments yet.
 Received an IDCW Payment: Is It All Profit? →
 Gold Has Fallen: Check This Before You Buy →
चर्चा / Comments