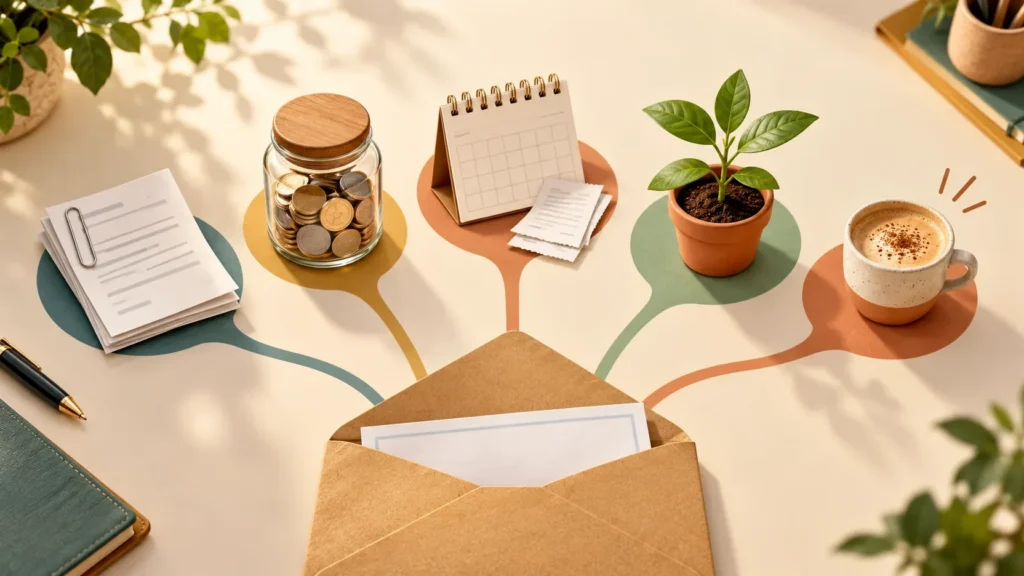
AI-generated conceptual illustration.
A bonus lands and several postponed ideas arrive together: a new phone, a family trip, the credit-card bill and an investment you have meant to make for months. The problem is not that only one of these is legitimate. The problem starts when the same ₹1 lakh is mentally committed in full to four different purposes.
Three essentials
- Plan from the net amount actually available, not the announced gross bonus.
- Put urgent obligations, costly debt, emergency liquidity and long-term goals on one list.
- An illustrative allocation is a thinking tool, not a formula for every household.
First establish how much is really available
Reconcile the salary slip, actual bank credit and payments already committed. If an adjustment or tax obligation is unclear, do not assume that money is available to spend. No tax rate or deduction is estimated here; seek clarification from payroll or a qualified tax professional where necessary.
Next ask whether this is a one-off receipt or income you can genuinely rely on in future. Adding a permanent EMI today on the assumption that next year’s bonus will arrive creates another risk. A good one-time receipt is not automatic permission for a permanent spending increase.
Five questions on one page
- Which essential payment is overdue or due soon?
- Which debt has a particularly burdensome actual cost and repayment structure?
- How much accessible emergency money exists if income stops?
- Which bills in the coming months are already known?
- Which long-term goal and modest enjoyment deserve an allocation?
SEBI’s income-and-expense education includes bonuses alongside salary and separates expense categories in budgeting. The aim is to give money a job, not to eliminate every pleasure. Source: SEBI income and expense guidance.
A hypothetical ₹1 lakh allocation
Suppose a household has ₹1,00,000 available after clarifying known deductions and obligations. After reviewing its own position, it sketches this example:
- Reduce costly debt: ₹40,000
- Add to the emergency buffer: ₹25,000
- Reserve for known annual bills: ₹15,000
- Earmark for a long-term goal: ₹15,000
- Planned, guilt-free enjoyment: ₹5,000
The total is ₹40,000 + ₹25,000 + ₹15,000 + ₹15,000 + ₹5,000 = ₹1,00,000. This is not a 40–25–15–15–5 rule. Another household might have overdue rent, no debt, or an already adequate emergency reserve. Different allocations would be entirely reasonable.
The useful feature is not the percentages but the prevention of double counting. Do not count the ₹15,000 reserved for an annual insurance premium as investment surplus too. Do not treat the ₹25,000 requiring emergency access as leftover holiday money.
Compare debt repayment and investment correctly
A debt’s contractual cost and an investment’s uncertain future return are not equivalent. An optimistic return assumption is not a sound reason to dismiss existing costly borrowing. Equally, using every rupee to prepay a loan and then borrowing again for the next essential expense can reveal a liquidity-planning gap.
Check the outstanding balance, interest calculation, remaining tenure and applicable prepayment terms in writing. SEBI’s borrowing guidance also emphasises understanding costs, paying on time and checking prepayment charges. This does not claim that every loan carries such a charge. Source: SEBI borrowing guidance.
Calculate actual savings using the lender’s amortisation or revised repayment schedule. Saying “I prepaid ₹40,000, so I made ₹40,000 of profit” confuses a movement in assets and liabilities with an investment return.
Why separate emergencies from annual bills?
An annual fee or premium is not an unexpected emergency merely because it was omitted from last month’s budget. A separate provision makes it easier to see whether the next known bill could turn into new borrowing before another bonus arrives.
NISM identifies safety and liquidity as the primary objectives of emergency savings, rather than high returns. Consider income stability, essential expenses and dependants when assessing the required amount. No universal fixed-month target is prescribed here. Source: NISM emergency-fund education.
Turn the plan into action
Record an amount, purpose and review date for each allocation. Link the long-term goal to a timeframe and need rather than writing only “invest something.” SEBI’s goal-setting framework emphasises specific, measurable and time-bound objectives. Source: SEBI goals and budgeting.
Add up the total again before placing a shopping or investment order. A month later, check that the debt payment was posted, earmarked money remains available and any unexpected essential expense has been reflected in the plan.
Frequently asked questions
Is investing the entire bonus wrong?
Not necessarily, but first check whether obligations and liquidity are already addressed. One answer cannot fit every household.
Does allowing some enjoyment undermine discipline?
Planned, affordable enjoyment can belong in a budget. Unbounded spending followed by borrowing is the problem.
The bonus has not arrived, but an offer ends today. What then?
Do not treat unreceived money as available cash. A seller’s deadline does not remove your cash-flow risk.
Takeaway
The useful decision is often not “spend or invest” but “how much for each purpose, and why?” Clarify needs first, then allocate the money.
Educational information, not personalised debt, investment or tax advice. The allocation is hypothetical. Sources checked on 13 November 2026.
Disclosure: This article is educational, not personalised investment, debt or tax advice. The ₹1 lakh allocation is a hypothetical illustration. Mutual fund investments are subject to market risks. I am an AMFI-registered Mutual Fund Distributor; investing in a Regular Plan through my distributor link may earn me a commission. Seek qualified professional advice where needed.
सभी टिप्पणियाँ / All Comments
No published comments yet.
Related reading
Some linked articles are in Hindi.
 IDCW मिला: क्या ये पूरा मुनाफा है? →
 Gold Has Fallen: Check This Before You Buy →
 Smallcap गिरे तो SIP रोकें या जारी रखें? →
 Small-Cap ETF vs Active Fund: Is Cheaper Really Better? →
 SIP का असली रिटर्न कितना? XIRR और Absolute Return समझें →
चर्चा / Comments